
‘Simple for customers, complex for company’: Freedom Payments CEO on fintech routine
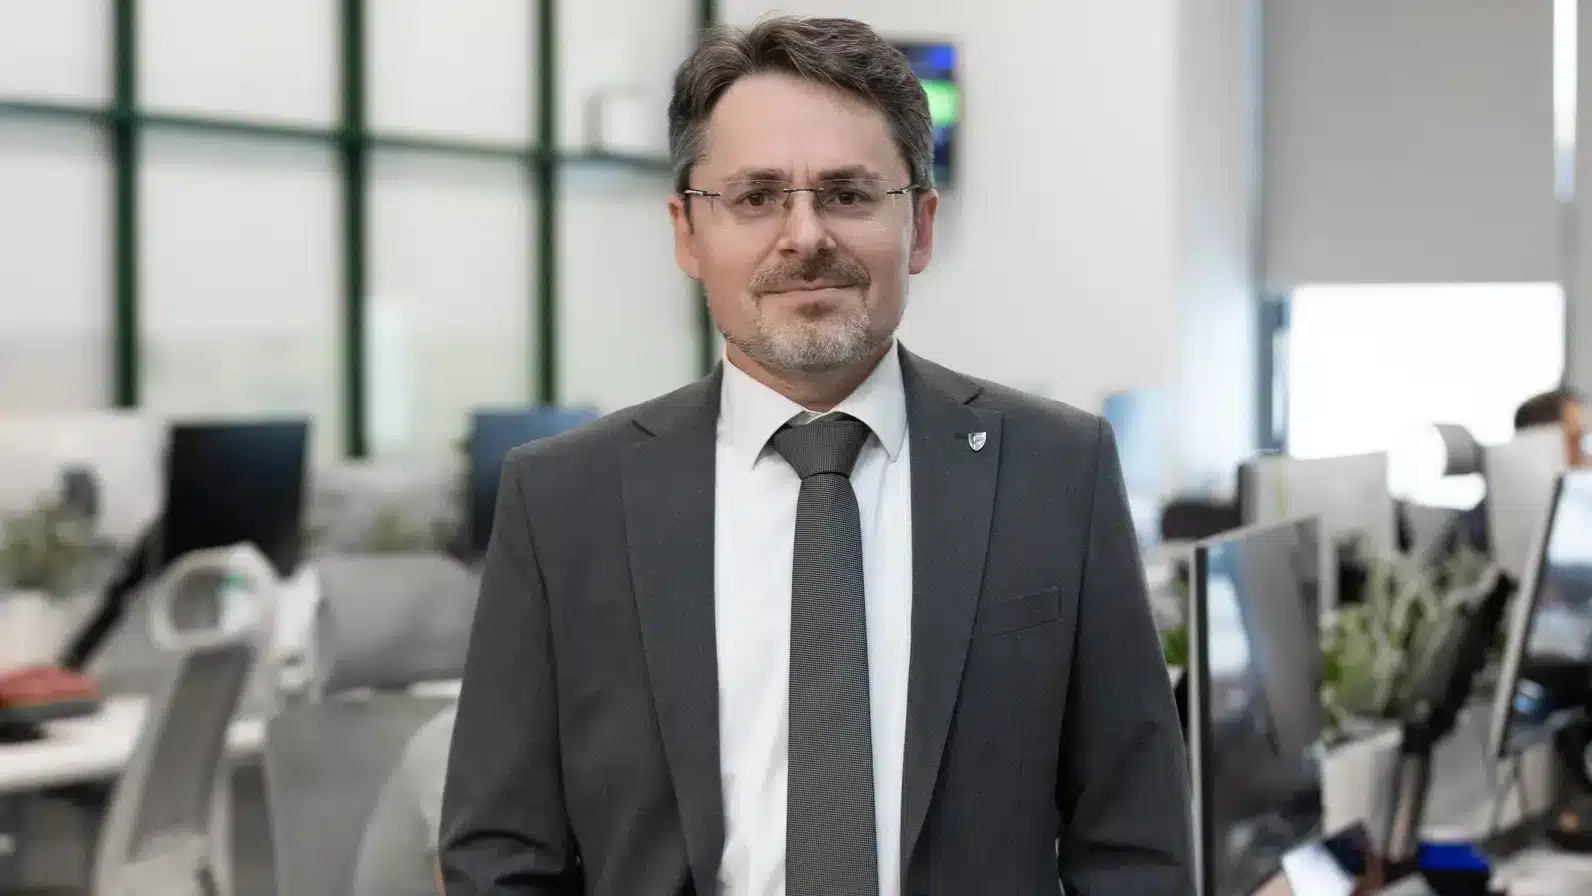
Just a few years ago, people perceived Freedom Payments, also known as PayBox, primarily as a traditional online acquiring service. Today, it is an infrastructure platform that processes more than 12 million transactions a month and is actively expanding beyond Kazakhstan into Uzbekistan, Kyrgyzstan and Tajikistan. Even though the company is part of a large parent holding company, almost all of its business comes from external clients. In this interview, Freedom Payments CEO Roman Minikeyev explained why the Freedom ecosystem needs a separate payment service alongside Freedom Bank, how artificial intelligence helps fend off cyberattacks and why smartphone payments — simple on the surface — rely on highly complex processes that remain invisible to users.
— When you joined PayBox in 2021, it was primarily an online acquiring service. What is Freedom Payments today? Where does acquiring end and a full-fledged payment infrastructure begin?
— In 2021, PayBox was indeed primarily associated with online acquiring. Today, Freedom Payments is a much broader payment infrastructure platform for businesses.
Acquiring remains one of our core business areas, but our role is no longer simply to accept payments on websites and process transactions. We now cover many more stages of the payment process, including various payment methods, recurring payments and tokenization, payouts, online fiscalization, payment links, QR payments, mobile wallets and other solutions.
In addition, we are developing infrastructure products for banks and major partners, including processing, payment gateways, card issuance and multi-acquiring.
The dividing line is roughly where a company stops being merely a payment acceptance service and starts managing the entire payment chain. Today, Freedom Payments is a technology partner that helps businesses not only accept payments but also build payment and fintech infrastructure around their specific needs.
— Freedom has its own bank. Why does the ecosystem need a separate payments company? What functions do you perform that cannot simply be transferred to the bank?
— Freedom Bank and Freedom Payments have different roles, which is precisely why it makes sense to develop them as separate businesses.
The bank primarily handles financial products: accounts, cards, lending, banking services and customer relationships. Freedom Payments has a different set of responsibilities. It provides the technology infrastructure for payment acceptance and processing, transaction routing, tokenization, fraud prevention and integration with payment systems.
Moreover, Freedom Payments isn’t limited to a single bank’s infrastructure. We can work with different banks, fintech companies and payment systems. Multi-acquiring is a good example: through a single integration, a business can work with several acquiring banks simultaneously, while payments can be routed between them according to predefined rules. If this platform were moved entirely into Freedom Bank, it would primarily become banking infrastructure. It is important for Freedom Payments to remain an independent technology layer capable of serving the entire market.
Having Freedom Bank within the ecosystem gives us additional opportunities. We can integrate banking and payment products more deeply and move faster from idea to finished solution.
For example, we can combine payment acceptance with business banking products, develop more sophisticated payout, tokenization and card-service scenarios, and create solutions at the intersection of acquiring, installment payments and other financial products. In this case, businesses receive an integrated payment solution rather than a collection of separate services from different providers.
That is why the value lies in combining these two areas of expertise.
— What volume of payments does your company process?
— We process around 12.5 million transactions per month, although this volume can fluctuate significantly. It depends primarily on our merchants’ activity, but external circumstances also play a role. For example, when other payment services experience outages, some customers may turn to us to process their payments. That is why we must not only handle current transaction volumes but also be prepared for sudden spikes in demand, ensuring that payments remain just as reliable as they are on a normal day.
— How dependent is Freedom Payments on large merchants?
— Large merchants are certainly important to Freedom Payments, and we value our long-term relationships with them. However, I wouldn’t say we are heavily dependent on individual clients. We work with companies across various industries, and the flexibility of our services allows us to consider their specific needs and adapt our solutions accordingly.
We also approach our relationships with merchants primarily as partnerships. We focus on understanding how a client’s business is developing, what it needs and where our solutions can add value. Our expertise, combined with continuous improvements in technology and processes, helps us strengthen cooperation with existing clients and identify new business opportunities.
We have already experienced significant changes in our merchant portfolio. Markets do not stand still: demand, operating conditions and legislation change. That is why we must not assume our customer base will remain unchanged but adapt our offerings and approaches on time. Our team knows how to operate in such conditions.
Of course, we value every long-term partnership and invest in developing these relationships. But for us, business resilience means a combination of strong customer relationships, a diversified portfolio and the ability to respond to market changes.
Read the full interview here.
